

Generation Wealth
Personal finance news, guides, and insights for life in Spain.

What the banks won’t tell you...
We will.

Latest Economic News


Latest Articles

How to Choose Your Account in Spain: Savings vs. Term Deposit vs. Investment
19 de octubre de 2026
Comparing savings accounts, term deposits, and investment options in Spain? Discover which account fits your financial goals, liquidity needs, and tax strategy.

Spain’s New SIALP Financia Europa: Invest Up to €10,000 a Year with Tax Benefits
19 de octubre de 2026
Spain’s new SIALP Financia Europa raises the annual investment limit to €10,000, with tax-free returns after five years for eligible investors.
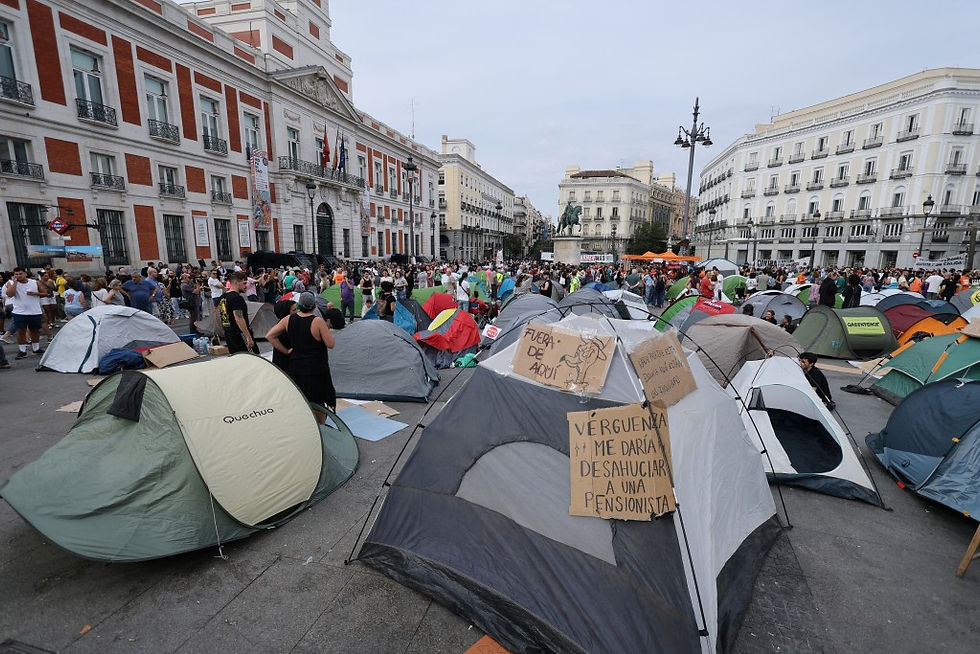
Spain Economy October 2026: Sánchez Calls Snap Election Over Housing Crisis as Inflation Hits 4.9%
5 de octubre de 2026
Spain’s Prime Minister Sánchez calls a snap election after Congress rejects housing measures. Meanwhile, Spaniards feel good about their finances but remain pessimistic about the economy.
Explore our Sections


Calculate your Mortgage
Calculate your monthly mortgage payments instantly with our Spain 2026 mortgage (hipoteca) calculator. Adjust the loan amount, interest rate, and term using interactive sliders, and compare fixed vs variable interest rates. See at a glance your monthly payment, total interest, and total amount to be paid—all in a clear, easy-to-use tool designed for Spanish home buyers.
Disclaimer: This mortgage calculator is for illustrative purposes only. It provides estimates and should not replace professional financial advice. Actual payments may vary based on your lender, credit profile, taxes, and fees. This mortgage calculator uses the 12-month Euribor, the reference rate that banks typically use to calculate variable mortgages in Spain.

What is a mortgage and how does it work?
A mortgage is a loan you take from a bank or financial institution to buy a home. You repay the loan in monthly installments, including principal and interest, over an agreed period. Understanding mortgage types is essential to choose the option that best suits your financial needs.
Fixed-rate mortgage: when is it recommended?
With a fixed-rate mortgage, the interest remains constant throughout the loan term. This allows predictable monthly payments, ideal if you prefer stability and want to protect yourself from future interest rate increases.
Variable-rate mortgage: advantages and risks
A variable-rate mortgage is linked to a reference index, like the Euribor. Your monthly payments can rise or fall depending on market fluctuations. It’s suitable if you expect interest rates to remain low or want to take advantage of temporary rate reductions, but it requires tolerance for variability.
Mixed or hybrid mortgage: what it offers
A mixed mortgage combines an initial fixed-rate period with a later variable rate. It’s ideal for those who want security at the beginning and later flexibility to benefit from potential market reductions.
Tips for choosing the right mortgage
Consider your payment capacity, timeline, and risk tolerance. Using mortgage calculators and simulators like this one, can help estimate total costs and decide between stability, flexibility, or a hybrid strategy. Understanding the differences between mortgage types enables better planning, helps optimize your finances, and ensures you make informed decisions when buying a home.